Navigating the ins and outs of auto loans can often feel like a maze, especially if you are balancing a busy routine around Dearborn and Metro Detroit. Whether you need an efficient daily driver for those quick morning commutes down Michigan Avenue or a capable vehicle for family weekends exploring The Henry Ford, securing the right payment plan shouldn't add stress to your day. Figuring out the financing puzzle is just a matter of having the right information at your fingertips.
That is why Village Ford-a family- and veteran-owned dealership-prioritizes a transparent, educational approach to vehicle financing. This guide is designed to break down the process of funding a new or pre-owned Ford step-by-step. From understanding how loan terms work to knowing what to expect when reviewing your options, our goal is to give drivers from Canton to Southgate the confidence to make informed choices that fit their lifestyle perfectly.
What Should I Know Before Applying for a Car Loan?
Getting ready to finance a new Ford Bronco or F-150 means doing a little homework first. What this means for Dearborn drivers is that taking charge of your finances upfront removes the guesswork, ensuring you find loan terms that comfortably fit your lifestyle. Whether your daily routine involves running errands near Fairlane Town Center or navigating the morning rush along I-94, understanding your borrowing power is the crucial first step toward bringing home the right truck or SUV without any added stress.
Your credit profile acts as the foundation for any financing offer. Start by requesting a free copy of your credit report from the major bureaus so you can view exactly what potential lenders will see. That three-digit score directly influences the interest rates you will qualify for. A strong credit history generally opens the door to lower annual percentage rates (APRs) on standard 36- to 72-month auto loans. If your current score needs a little work, spending a few months paying down balances or correcting report errors can make a significant difference. Plenty of free, reputable credit-education websites exist to help you build a strategy to improve your standing over time.
Beyond the credit score, mapping out a realistic budget keeps you firmly in the driver's seat. It is easy to just look at a vehicle's sticker price, but you also need to account for ongoing expenses like auto insurance, routine maintenance, and fuel. Financial experts typically recommend keeping your total automotive expenses under 15 to 20 percent of your monthly take-home pay.
To put that rule of thumb into perspective, if you commute from Dearborn Heights into downtown Detroit via Michigan Avenue, your weekly fuel budget will look very different in a gas-powered Explorer compared to a highly efficient Escape Plug-in Hybrid. Running your numbers through an online auto loan calculator lets you plug in various down payments, trade-in values, and expected interest rates. This quick calculation provides a much clearer picture of your future obligations, helping you zero in on a monthly payment bracket that feels completely manageable for your household.
How Do I Get Approved for Ford Financing?
Securing an auto loan for a new or used Ford comes down to submitting a straightforward credit application and providing proof of your financial standing. You can knock this out from your living room before heading out to shop near Fairlane Town Center, or sit down with our finance experts right here at the dealership. Either way, we take your application and work directly with Ford Credit, alongside a network of local and national lenders, to track down terms that fit your budget.
What this means for drivers around Dearborn and nearby Canton is that getting pre-approved ahead of time removes the guesswork, letting you focus entirely on finding the right truck or SUV for your daily runs down Michigan Avenue. Here's exactly what you'll need to gather to get the ball rolling.
Personal Information: Start with the basics. You'll need your full legal name, current residential address, date of birth, and Social Security number so lenders can securely pull your credit profile.
Employment and Income: Banks look for stability. Be prepared to share your current employer's details, your job title, and verifiable gross income. Having your last 30 days of pay stubs or recent W-2s on hand typically speeds up the verification process.
Vehicle Information: Lenders need to know what you're buying to properly structure the loan. You'll provide the exact year, make, model, and trim-like a gas-powered 2027 Ford Explorer or a hybrid 2026 Ford Maverick-along with the total purchase price.
Once your application goes into the system, lending partners evaluate your debt-to-income ratio, credit history, and the size of your down payment. Ever wonder why putting a little extra cash down upfront helps? Bringing a 10% to 20% down payment to the table reduces the total amount you finance, which lowers the lender's overall risk and often unlocks more favorable interest rates. While final approval and exact terms always depend on your specific credit profile and income, our objective is to present you with competitive financing offers so you can confidently take the keys.
What Do Different Loan Terms Mean?

When you review an auto loan offer for a new Ford F-150 or Escape, the contract can look like a maze of financial jargon. For families running weekend errands near Fairlane Town Center or professionals tackling the daily commute down I-94, understanding these definitions is how you secure a dependable vehicle without stretching your budget. It all boils down to how much you pay upfront, the length of your contract, and the true cost of borrowing.
APR (Annual Percentage Rate): This figure represents the total yearly cost of financing your vehicle. Unlike a simple interest rate, the APR rolls in both the interest charged by the bank and any standard lender fees. A lower APR directly reduces the total amount of money you will spend over the life of the loan, keeping more cash in your pocket.
Loan Term: This refers to the number of months you have to pay off the balance, with most auto loans ranging between 36 and 84 months. Stretching a loan from 60 months out to 72 months will noticeably drop your monthly payment, but you will pay more in cumulative interest over that extra year. Conversely, a shorter term means larger monthly drafts, but you will own your Ford Bronco Sport free and clear much sooner.
Down Payment: This is the initial cash, or trade-in equity, you apply toward the purchase before the financing even kicks in. Putting down 10% to 20% on a spacious Ford Explorer shrinks the principal loan amount right out of the gate. This not only lowers your monthly payment but also acts as a buffer against depreciation as you put miles on the odometer navigating stop-and-go traffic along Schaefer Road.
To map out a strategy that fits your lifestyle, you can easily estimate your current car's trade-in equity using trusted industry resources like Kelley Blue Book. Reviewing these details ahead of time ensures you can sign your paperwork with total confidence.
Can I Finance a Pre-Owned Ford?
Securing an auto loan for a used or Certified Pre-Owned (CPO) Ford is incredibly common and straightforward. In fact, the paperwork and approval steps closely mirror what you would experience when buying a brand-new model. What this means for Dearborn drivers is that you get the flexibility of manageable monthly payments without absorbing the initial depreciation hit of a fresh-off-the-line vehicle.
Lenders frequently view Ford Gold Certified vehicles with high confidence because these cars and trucks maintain excellent resale value. Before earning that badge, every Gold Certified model must pass a mandatory 172-point inspection to ensure mechanical and cosmetic quality. That expert sign-off, combined with a robust 7-year/100,000-mile Powertrain Limited Warranty, shows banks that the asset is built to last. Because the lender's risk is lower with a rigorously vetted and warrantied vehicle, buyers can often secure highly competitive interest rates compared to standard used auto loans.
Whether you need a spacious Ford Explorer for weekend outings to The Henry Ford museum with the family, or a fuel-efficient Escape for your daily commute down Michigan Avenue and through neighboring Allen Park, financing makes it highly accessible. Even upgrading to a capable F-150 with 4WD to handle unpredictable winter weather around Southgate and Canton becomes easier to budget. If you want to research fair market values and ownership costs before applying for credit, trusted automotive sites like Edmunds offer excellent pricing data and reviews to help you make a smart, informed investment.
How Does a Trade-In Affect My Auto Loan?
Trading in your current car directly shrinks the total amount you need to borrow for your next vehicle, functioning exactly like a cash down payment. What this means for Dearborn drivers commuting along Michigan Avenue or running errands near Henry Ford College is that a solid trade-in value immediately lowers your monthly payments and cuts down on the total interest you will pay over the life of the loan.
Let's look at how the math actually plays out. Suppose you are eyeing a hypothetical $30,000 gas-powered Ford Escape, and your older car is appraised at $5,000. Applying that trade-in value means you only need to finance $25,000, plus any applicable taxes and state fees. By dropping the principal by five grand right out of the gate, you reduce the compounding interest applied over a standard 60-month term, keeping more money in your bank account.
The appraisal process itself is built around your schedule. While you take a new Ford for a test drive, a professional can evaluate your outgoing car and present a transparent, no-obligation number. To make sure you feel entirely confident in that offer, doing a little homework ahead of time goes a long way. You can easily cross-check current market pricing through independent organizations like Consumer Reports, which delivers unbiased valuation data. Understanding your car's true worth helps ensure you walk away with a fair deal that sets up your next auto loan for success.
Frequently Asked Questions (FAQs)
How does Village Ford ensure transparency during the financing process?
Since opening our doors in 1982, Village Ford has maintained an unwavering commitment to automotive excellence, earning the prestigious Ford Motor Company President's Award 13 times. Our finance team treats you like a valued member of our family, carefully walking you through every detail of your Ford Credit agreement to guarantee complete transparency before you drive home to Allen Park or Canton.
How can I ensure that I understand all terms before signing?
To ensure you understand all terms, the dedicated team at Village Ford will leverage our over four decades of deep expertise to review your entire contract alongside you. We provide a tailored dealership experience for every client, meaning our professionals patiently explain your financing rates and conditions so you feel completely confident hitting the roads around Dearborn Heights and Southgate.
What are my rights regarding financing agreements?
When working with Village Ford, our staff ensures you fully understand your rights by actively guiding you through every aspect of the paperwork. We draw on our lifetime of industry authority to explain your options clearly, delivering the exceptional, tailored dealership experience that has supported drivers from Taylor to Detroit since 1982.
How does Village Ford provide clear, upfront pricing to prevent unexpected fees after financing a vehicle?
Village Ford prevents surprise costs by taking a highly detailed, upfront approach to your automotive financing. Because we treat you like a valued member of our family, our staff breaks down the exact out-the-door price of your new vehicle, ensuring complete financial clarity for our neighbors across Melvindale and Dearborn.
What awards has Village Ford earned for its sales and service?
Village Ford has earned the prestigious Ford Motor Company President's Award 13 times for our unwavering commitment to automotive excellence. In addition, we have received six rare Triple Crown awards, which recognize our elite status nationwide across sales, service, and parts for drivers throughout Dearborn and the surrounding communities.
How does Village Ford support the local communities it serves?
Beyond our showroom and state-of-the-art service center, Village Ford maintains an active local presence through strategic community sponsorships. We build partnerships that directly support the neighborhoods we call home, ensuring we give back to areas like Dearborn Heights, Taylor, and Allen Park while providing premier automotive resources.
About Village Ford
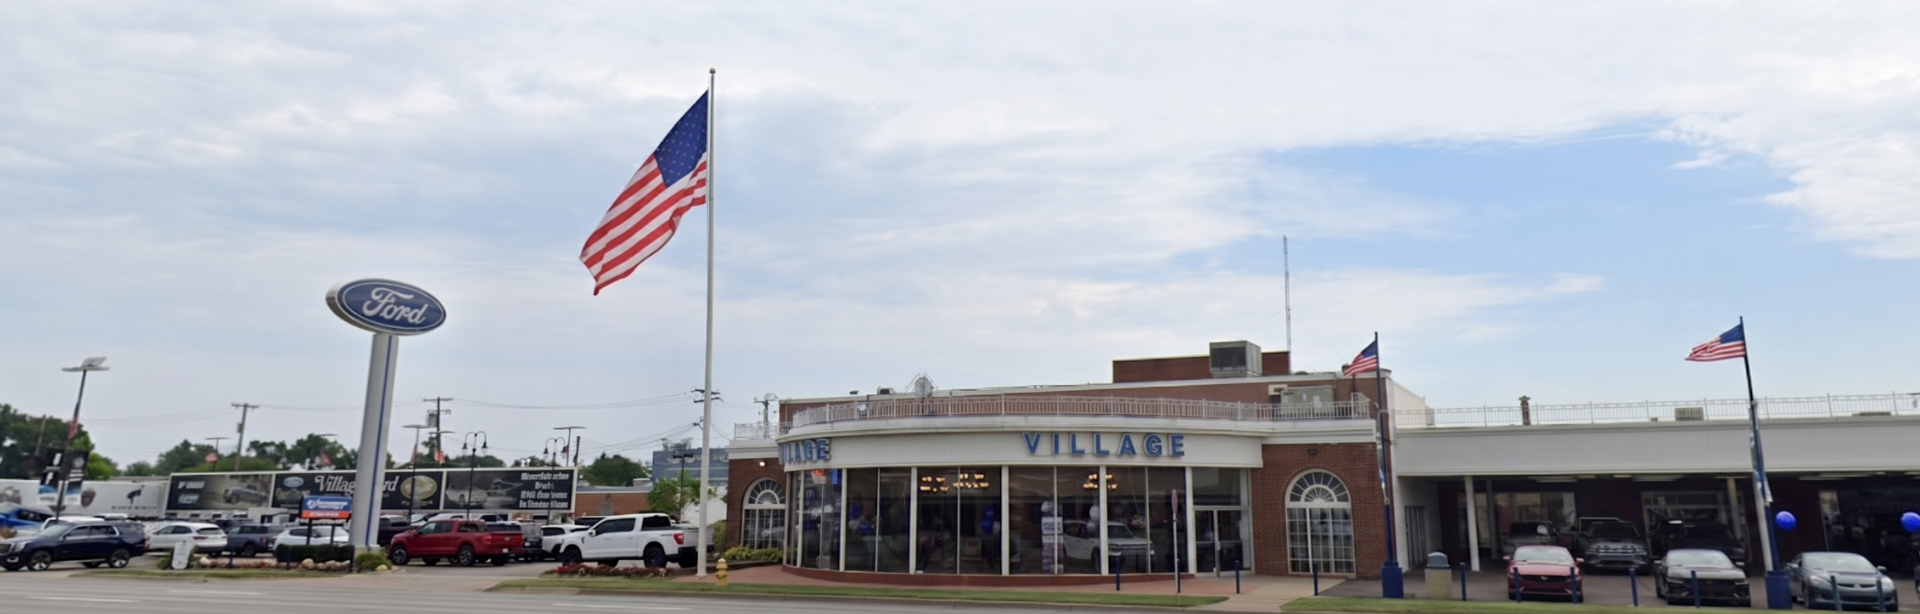
As the team at Village Ford, we are proud to serve as your premier automotive resource in Dearborn, Dearborn Heights, Taylor, Melvindale, Allen Park, and the surrounding communities. Since opening our doors in 1982, we have dedicated over four decades to building deep expertise and providing an exceptional, tailored dealership experience for every client. Our unwavering commitment to automotive excellence has earned us the prestigious Ford Motor Company President's Award 13 times, alongside six rare Triple Crown awards recognizing our elite status in sales, service, and parts nationwide. Beyond our showroom and state-of-the-art service center, we maintain an active local presence through strategic community sponsorships and partnerships that directly support the neighborhoods we call home. Whether you are seeking a reliable new vehicle or trusted vehicle maintenance from our certified technicians, we leverage our lifetime of industry authority to treat you like a valued member of our family.Related Articles:
Finding Your Ideal Ford Dealer in Dearborn, MI: A Comprehensive Guide